
You opened a business to build something — not to argue with spreadsheets about when revenue "counts." Yet the accounting method you choose quietly shapes every tax return you file, every loan application you submit, and every gut-check you do on whether the business is actually profitable. Get it wrong and you're either paying taxes on money you haven't collected yet or showing lenders a picture of your finances that doesn't hold up under scrutiny.
Here's the plain-English breakdown of cash versus accrual accounting, when the IRS forces your hand, and how to figure out which method actually serves a Northeast Indiana business like yours.
What Is the Difference Between Cash and Accrual Accounting?
Cash-basis accounting records income when money hits your bank account and expenses when you actually pay them. Accrual accounting records income when it's earned and expenses when they're incurred — regardless of when cash changes hands. The difference sounds subtle, but it can swing your taxable income by tens of thousands of dollars in a single year.
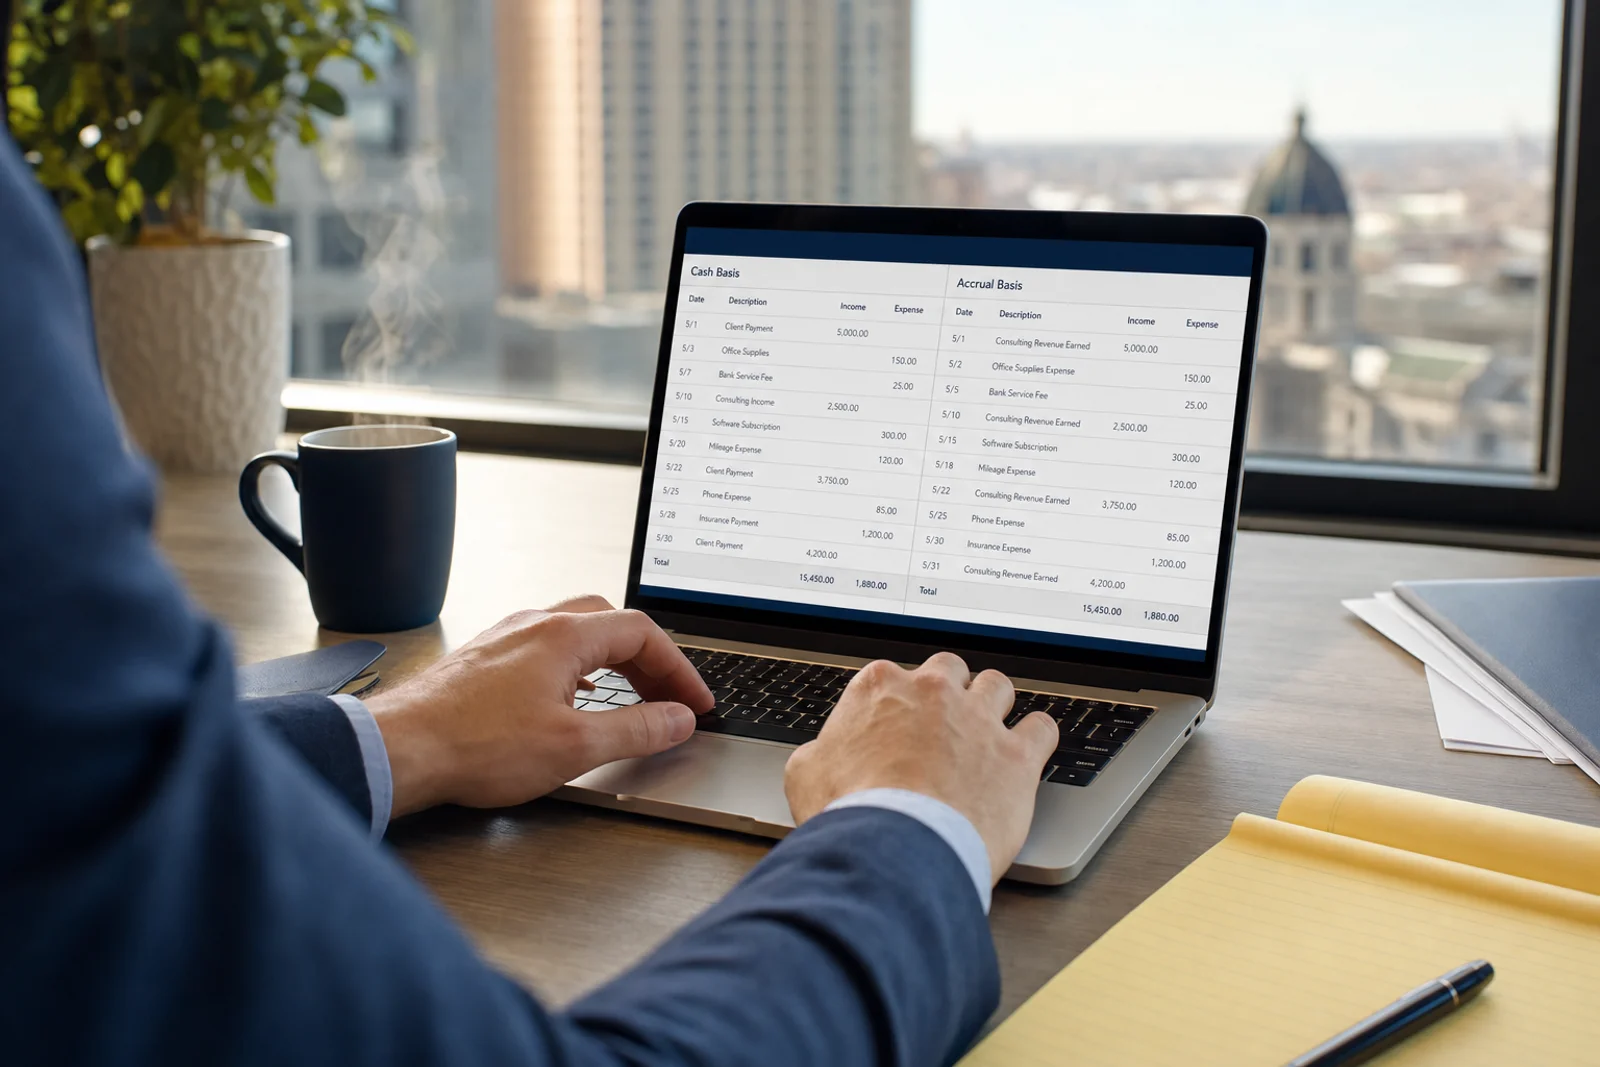
Think about a Fort Wayne manufacturing shop that completes a $40,000 job on December 28 but doesn't get paid until January 15. Under cash basis, that revenue shows up in January — next year's tax return. Under accrual basis, it hits December — this year's return. Same work, same money, dramatically different tax timing.
Here's a quick side-by-side:
Feature Cash Basis Accrual Basis Revenue recognized When received When earned Expenses recognized When paid When incurred Simplicity Higher Lower Accuracy of financial picture Lower Higher Required for GAAP reporting No Yes
When Does the IRS Require the Accrual Method?
The IRS mandates accrual accounting for certain businesses, primarily those with significant inventory or above a gross-receipts threshold. Under the Tax Cuts and Jobs Act of 2017, the IRS raised the average annual gross receipts threshold — meaning more small businesses now qualify to use cash basis than before.[1]
Specifically, the IRS generally requires the accrual method if your business:[2]
Is a C corporation (with limited exceptions) or a partnership with a C corporation partner that has average annual gross receipts exceeding $31 million (indexed for inflation as of 2024).
Is required to account for inventories under IRC §471 and does not qualify for the small-business inventory exception.
Is a tax shelter as defined under IRC §448(d)(3).
Most sole proprietors, S corporations, partnerships without C corp partners, and LLCs taxed as pass-throughs can use cash basis if their average annual gross receipts for the prior three years don't exceed the threshold. Our business tax preparation team reviews your gross receipts calculation every year to make sure you're using the right method — and not leaving a compliance gap open for an IRS challenge.
Which Method Gives You a More Accurate View of Your Business Health?
Accrual accounting gives a truer picture of profitability because it matches revenue to the period in which it was earned and expenses to the period in which they were incurred — a concept accountants call the "matching principle." Cash basis, by contrast, can make a business look flush one month and starving the next, simply because of billing cycles.
Consider a construction subcontractor in Allen County who bills $80,000 in November but won't collect until February. Under cash basis, November looks like a loss month and February looks like a windfall — even though the work (and the cost of doing it) all happened in November. Owners making hiring or equipment decisions based on that distorted view can get into serious trouble.
That said, accrual accounting requires tracking accounts receivable, accounts payable, and deferred revenue — which adds bookkeeping complexity. If your transactions are simple and you collect payment quickly, cash basis may give you plenty of clarity without the overhead. Clean, consistent bookkeeping is the foundation either way; the method just determines the rules your bookkeeper follows.
What Are the Tax Planning Implications of Each Method?
Cash basis gives you more direct control over taxable income in a given year. If you expect to be in a lower tax bracket next year, you can delay sending invoices in late December so income lands in January. You can also accelerate deductible expenses — prepaying rent, insurance, or supplies — before year-end. This kind of timing flexibility is a core lever in year-end tax planning.
Accrual basis narrows that flexibility. Revenue is recognized when earned, so you can't simply hold an invoice to shift income. However, accrual accounting does allow you to deduct certain accrued but unpaid expenses (like year-end bonuses owed to employees) in the year they're incurred, provided they're paid within 2½ months of year-end under IRC §461.[3]
One often-overlooked point: if you want to switch accounting methods, you can't just flip a switch on January 1. You must file IRS Form 3115 (Application for Change in Accounting Method) and account for a "Section 481(a) adjustment" to prevent income or deductions from being double-counted or missed.[4] This adjustment can be spread over four years or taken all at once, depending on the direction of the change. Consult your CPA / EA team at Warrior before making any switch — the timing of the adjustment can itself become a planning tool.
Which Accounting Method Makes Sense for Your NE Indiana Business?
For most early-stage or owner-operated businesses in Fort Wayne and surrounding counties, cash basis is the practical starting point — it's simpler, it mirrors your bank statement, and it reduces bookkeeping costs. As your business grows, takes on inventory, seeks outside financing, or brings in partners, accrual accounting typically becomes the better fit and may become mandatory.
Here's a general rule of thumb by business type:
Freelancers, consultants, service providers — Cash basis usually works well and is permitted.
Retail or product-based businesses with inventory — Accrual is often required or strongly advisable.
Construction and trades — Long-term contracts may require the percentage-of-completion method, a variation of accrual. Requirements depend on contract size and business gross receipts.[2]
Healthcare practices — Accrual is common given insurance billing cycles and complex receivables.
Manufacturing — Inventory rules typically push manufacturers toward accrual.
S corporations seeking outside investment or an eventual exit — GAAP-compliant accrual financials are typically expected by buyers and lenders.
If you're unsure where you fall, it's worth a conversation with the CPA / EA team at Warrior Business Services. The right method isn't just a compliance checkbox — it's a decision that affects your taxes, your financial clarity, and your ability to plan for growth.
Sources
- Tax Cuts and Jobs Act, Pub. L. No. 115-97, §13102 — Modifications to Rules for Expensing Depreciable Business Assets; Small Business Accounting Method Reforms. U.S. Congress. 2017. https://www.congress.gov/bill/115th-congress/house-bill/1/text
- Publication 538: Accounting Periods and Methods. Internal Revenue Service. 2024. https://www.irs.gov/publications/p538
- Internal Revenue Code §461 — General Rule for Taxable Year of Deduction. U.S. Code, Title 26. https://uscode.house.gov/view.xhtml?req=granuleid:USC-prelim-title26-section461
- Form 3115: Application for Change in Accounting Method (and Instructions). Internal Revenue Service. 2024. https://www.irs.gov/forms-pubs/about-form-3115

Written by
Warrior Business Services
Warrior Business Services is a boutique CPA firm in downtown Fort Wayne, Indiana, advising family-owned businesses and growth-minded owners across Northeast Indiana.